Insight
5 min read
Published on:

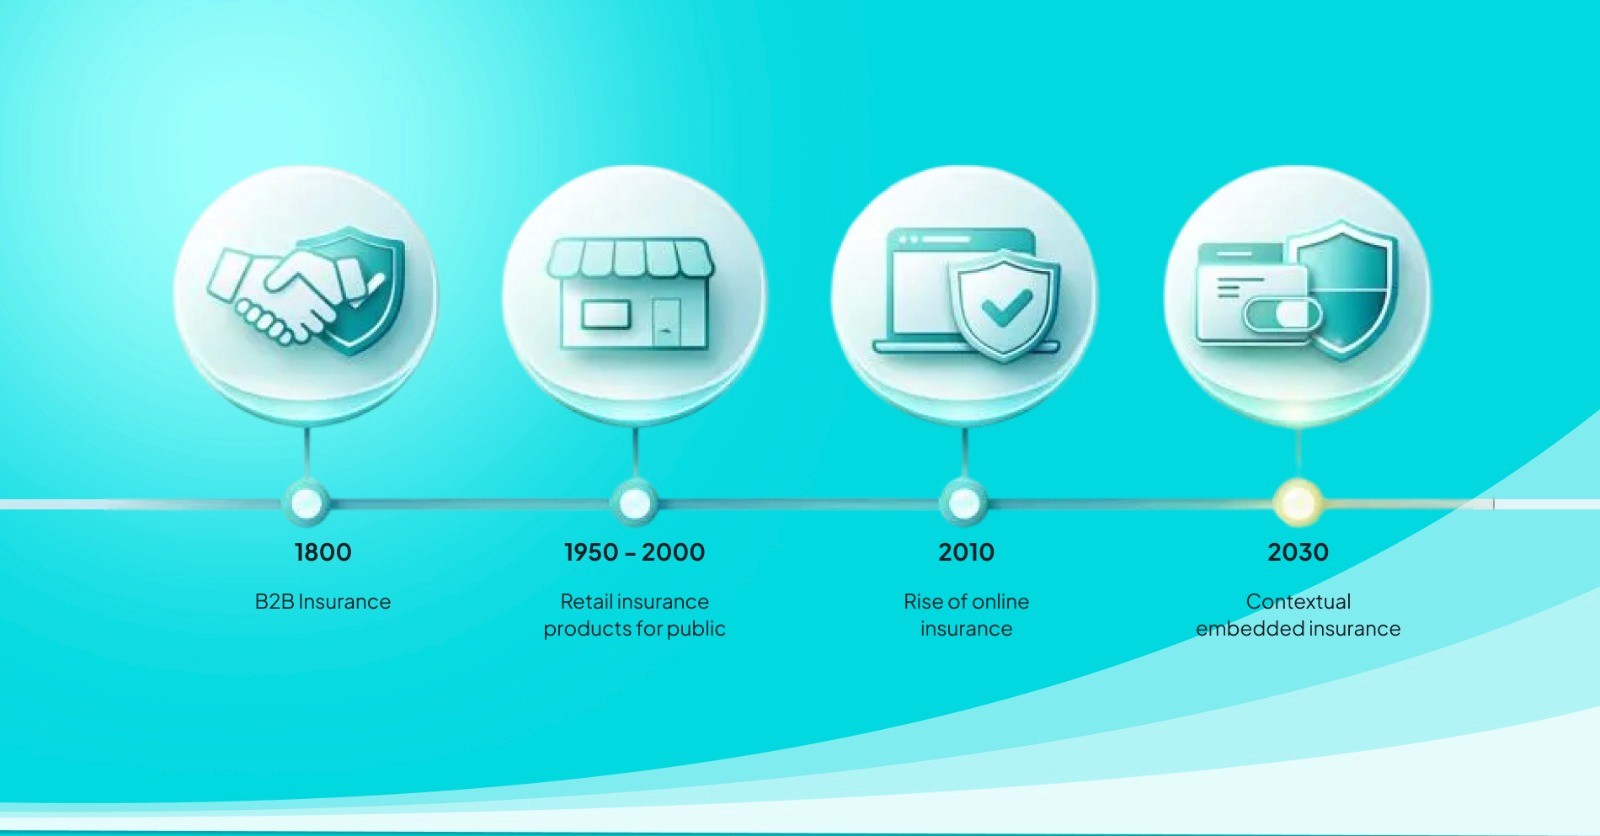
Insurance distribution is broken. Not struggling. Not inefficient. Fundamentally broken at a structural level that can’t be fixed by incremental improvements. The future isn’t traditional insurance companies getting better at digital distribution. It’s insurance disappearing into the transactions that create risk in the first place.
The distribution model that can’t survive
Traditional insurance distribution costs too much for what it delivers. An insurance company spends money to make you aware they exist. Spends more money to convince you that you need their product. Then spends even more money processing your application, underwriting your risk, and onboarding you as a customer.
This only works economically when policies have high premiums or long retention periods. Life insurance, health insurance, auto insurance. Big commitments that last years. The acquisition cost gets absorbed over the lifetime value. But most insurance people actually need doesn’t fit this profile. Device protection lasting two years. Travel coverage for a single trip. Rental protection for a week. Shipping insurance for one delivery.Traditional distribution can’t serve these categories profitably. The customer acquisition cost exceeds the policy value. The math simply doesn’t work.
Embedded insurance doesn’t have a customer acquisition cost. You’re not acquiring a customer. You’re offering protection to someone already buying something from you. The marginal cost of adding insurance to an existing transaction is nearly zero. This isn’t a better distribution model. It’s a completely different economic structure that makes entirely new categories of insurance viable.
Why behaviour change isn’t coming, it’s already here
Younger buyers don’t research insurance. They won’t start. They’ve grown up in a world where everything happens in one place. You don’t go to separate websites to handle payments, shipping, customer service. It all happens within the platform you’re already using.
Insurance being a separate decision requiring research and comparison isn’t just inconvenient to them. It’s structurally foreign to how they expect things to work.This isn’t about preference. It’s about baseline expectations formed by every other digital experience they’ve had. Insurance asking them to leave a platform, research options, compare policies, and come back later doesn’t align with any other part of their digital life.
And these aren’t future buyers. They’re current buyers. The generation that expects embedded experiences is already the largest spending demographic. This shift isn’t theoretical. It’s happening now.
The structural inevitability
Every product category that can be embedded eventually becomes embedded. Not because it’s slightly better. Because it makes structural sense in a way the old model didn’t. Music was sold as standalone albums. Then streaming embedded music in subscription platforms. You don’t buy music anymore, you access it within Spotify. Software was sold as standalone licenses. Then SaaS embedded software in subscription services. You don’t buy software anymore, you subscribe to platforms.
Payments were standalone transactions. Then platforms embedded payments in checkout flows. You don’t think about payment processors anymore, you just pay through the platform. Insurance is following the exact same path. And the reason is structural, not convenience.Insurance protects against risks created by specific activities. Phone insurance protects a phone purchase. Travel insurance protects a trip. Rental insurance protects a rental.
The risk and the insurance are directly connected. So why would they be separate decisions? The only reason insurance was ever a separate purchase is because distribution was separate from product sales. That made sense when retail was physical and insurance was sold through agents.Now that transactions are digital and platforms control the entire experience, that separation is artificial. Insurance logically belongs at the point of the transaction creating the risk. This isn’t about making insurance more convenient. It’s about insurance finally being structured correctly.
Why platforms will win the customer relationship
The power dynamic in insurance is shifting permanently from insurers to platforms.Traditional insurance companies own customer relationships. They decide policy terms, control pricing, handle claims, manage renewals. Distribution partners are just channels sending customers their way.Embedded insurance inverts this completely. Platforms own the customer relationship. They control when insurance appears, how it’s presented, what coverage is included, how claims are handled. Insurance companies become infrastructure providers operating behind the scenes.
This shift is irreversible once it starts. Platforms have no incentive to send customers to standalone insurance companies. Why would they? That creates friction, increases drop-off, and hands control to someone else. The more platforms embed insurance, the less reason customers have to think of insurance as a separate category. It just becomes a feature of buying things.
And once that mental model changes, traditional insurance distribution doesn’t recover. You can’t convince people to go back to researching and comparing policies when they’ve gotten used to protection just being included.
The unlock of new insurance categories
Traditional insurance can only exist for risks that justify the distribution cost. That’s a narrow set of scenarios. Embedded insurance removes this constraint entirely. Suddenly you can offer insurance for things that were never economically viable before. Micro-duration coverage. Hyper-specific protection. Dynamic policies that activate and deactivate based on actual usage.
A gig worker’s insurance that only covers them when they’re actively working. A traveler’s policy that activates during trips and pauses between them. Device protection that scales based on how intensively the device is being used. None of this works in traditional insurance. The administrative overhead of managing these dynamic policies would exceed the premium collected.
But embedded insurance can handle this because the platform already knows the context. When is the gig worker active? When is the traveler traveling? How is the device being used? The platform has this data. Insurance can simply plug into it. This isn’t just more insurance. It’s insurance that actually matches how people live and work, not standardized policies designed for administrative convenience. The categories this unlocks are massive. Every transaction, every activity, every interaction on digital platforms becomes an opportunity for contextual protection.
Why regulation accelerates this, not slows it
The common concern is regulation will kill embedded insurance. The opposite is true. Regulators want customers protected. They want clear terms, fair pricing, efficient claims. Embedded insurance can deliver this better than traditional insurance.Traditional insurance has complexity as a feature. Complicated terms. Hidden exclusions. Slow claims processes. This complexity exists partly because insurance companies control the experience and can make it difficult.
Platforms can’t afford this complexity. They need seamless experiences. Difficult insurance processes damage their core business. So they’re incentivized to make insurance simple, clear, and fast.Regulators will see this and push for embedded insurance to become the standard. Why let traditional insurers maintain complex, customer-hostile processes when platforms are proving simpler approaches work?
The regulatory trend will be toward requiring insurance to be offered at point of sale for high-risk transactions. Not allowing it. Requiring it.This is already happening in some categories. Regulators mandating certain protections be offered at checkout. That trend expands, not contracts.
Where traditional insurance still exists
Traditional insurance doesn’t disappear. But it becomes specialized. Complex, long-term coverage that requires customization stays with specialists. Life insurance. Commercial insurance. Large liability policies. These need expertise platforms don’t have.
But transactional insurance, protection tied to specific purchases or activities, moves entirely to embedded models. There’s no reason for it to exist separately anymore.The insurance market splits into two: specialist insurers handling complex products, and embedded insurance handling everything else.The embedded category becomes significantly larger. Because it includes all the insurance that traditional distribution made economically impossible.
What this means practically
At Assurekit, we’re building for the embedded future because it’s not a future, it’s the present. Platforms need insurance infrastructure that works the way their platforms work. Fast, integrated, seamless. Not insurance products bolted on top. We’re building that infrastructure. Not because embedded insurance might win. Because it’s already winning, and the platforms that figure this out early will own significant advantage. The question isn’t whether insurance becomes embedded. It’s how quickly platforms adapt to this reality.
The future of insurance is embedded because the economics work, the behavior has already shifted, the structure makes sense, and the alternatives don’t survive.That’s not prediction. That’s just recognizing what’s already happening.
Frequently asked questions

Written by