Products
5 min read
Published on:
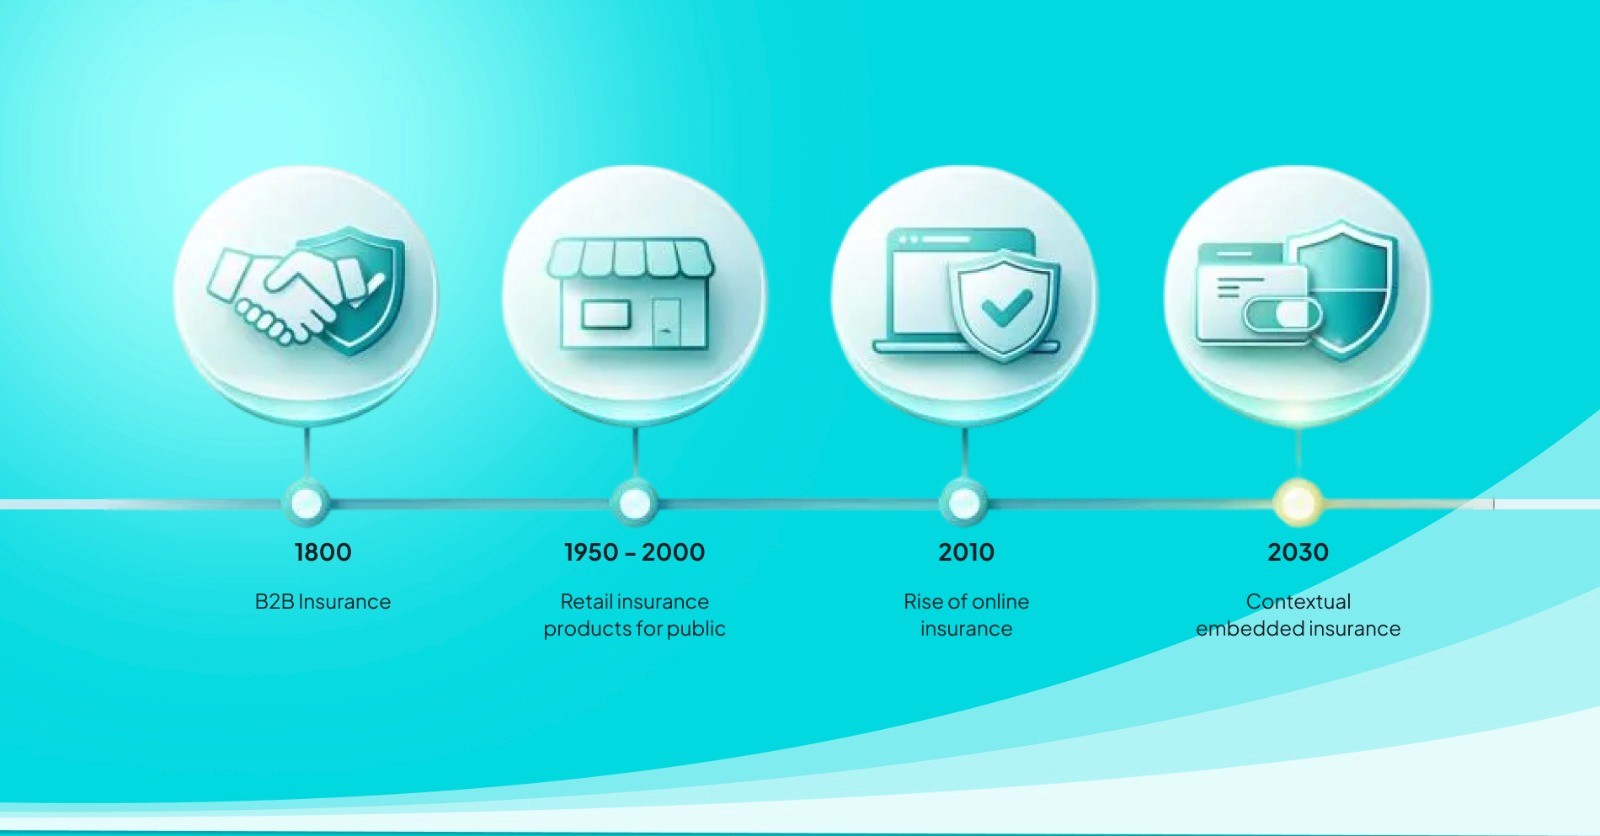
The future of embedded insurance: why insurers need to act today
Most traditional insurers have tried embedded insurance. A partnership with an e-commerce site, maybe a travel booking platform. The results were disappointing. Low conversion rates, minimal premium, high operational hassle. The conclusion: embedded insurance doesn’t work for us.
But here’s what’s actually happening. While most traditional insurers wrote off embedded insurance as unviable, a few insurers figured out what actually works. Those insurers are now generating ₹50-100 crore annual premium per major platform partnership. And the gap between insurers who’ve figured this out and those who haven’t is widening fast.
Why most embedded insurance experiments fail
The typical insurer approach: take an existing product, build an API, partner with a platform, launch. Maybe it’s travel insurance on a flight booking site or device protection on an e-commerce platform. Conversion rates come in at 2-4%. The platform loses interest. Everyone moves on.
The problem isn’t the channel. It’s trying to embed products designed for traditional distribution.
Consider device protection. A traditional product might cover manufacturing defects, accidental damage, theft, and liquid damage, each with different claim processes and documentation requirements. Customers need to read through coverage details, understand exclusions, and fill in device serial numbers.
That product was designed for someone in a retail store with a salesperson explaining coverage. Put it in a 30 second checkout flow on an e-commerce site and conversion drops to single digits.
What actually works: “Screen breaks, we replace it. ₹799. Claim online in under 24 hours.” Simple pricing, simple promise, simple claims. Products rebuilt from scratch for embedded contexts, not adapted from existing ones.
The insurers seeing 15-20% conversion rates in embedded insurance have product teams dedicated to building for digital distribution. The ones seeing 2-4% are using traditional products with minor modifications.
The unit economics that make sense
Traditional insurers look at embedded insurance and see small premiums per policy. ₹500 for travel insurance, ₹800 for device protection, and ₹50 per month for gig worker accident cover. Compare that to a ₹20,000 annual premium for a term insurance policy and embedded looks unattractive.
But look at actual numbers from working programmes:
A major e-commerce platform sells approximately 2 million smartphones annually. They offer screen damage protection at checkout for ₹799. At 18% conversion, that’s 360,000 policies. ₹28.8 crore in annual premium from a single product.
The platform takes 40-50% as a revenue share; the insurer keeps the rest. Loss ratios on device protection run 50-60%. Operating costs for automated programmes are 10-15%. That leaves 25-35% margins.
Acquisition cost? Nearly zero. The platform is already acquiring customers. You’re piggybacking on their traffic.
Compare that to traditional device insurance sold through retail. Acquisition costs alone consume 30-40% of first year premium. Break-even takes 18-24 months if customers renew.
The economics of embedded insurance work when you have volume. A single platform with 2-3 embedded products can generate ₹50-75 crore in annual premium. An insurer working with 5-6 major platforms across different verticals is looking at meaningful book contribution.
The technology investment that actually matters
“Too much work” usually means technology. And the investment is real. But most insurers focus on the wrong technology.
Traditional insurers think they need APIs. So they wrap APIs around existing policy admin systems and expect platforms to integrate. But those systems were built for agent sales processing hundreds of policies per day, not embedded distribution processing thousands.
What embedded insurance actually requires:
Real-time policy issuance: Under 10 seconds from purchase to policy document. Traditional systems can’t do this consistently at volume.
Automated underwriting: No forms, no manual review. Underwriting happens based on data the platform already has. This needs rule engines most traditional insurers don’t have.
Digital claims processing: Customers expect to file claims through the platform with the same ease they buy products. Manual claims review doesn’t work.
The insurers succeeding in embedded insurance either rebuilt their tech stack or partnered with insurtechs providing this infrastructure. Upfront investment is substantial. But once built for one partnership, adding additional platforms becomes progressively easier.
A traditional insurer might spend ₹5-8 crore building proper embedded insurance infrastructure. That sounds expensive until you compare it to what they spend annually on agent commissions or advertising, with much lower returns.
The distribution access that’s hard to value
Embedded insurance gives insurers access to customers traditional distribution can’t reach. Not “can reach but hasn’t yet.” Genuinely can’t reach.
India has 15 million gig workers. Delivery partners, drivers, freelancers. These people need insurance. Income protection, accident cover, health insurance. But they’re not meeting with insurance agents. They’re not visiting offices. They’re working 12-hour days trying to maximise earnings.
Platforms employing these workers can offer insurance during onboarding or through their apps. Uptake rates run 40-50% when products are priced right. These are customers generating premium that simply wouldn’t exist through traditional distribution.
Same story in e-commerce. The person buying a ₹15,000 phone online on EMI might not be able to afford standalone device insurance at ₹3,000. But embedded protection at ₹799? That converts. Again, a premium that wouldn’t exist otherwise.
Traditional insurers measure embedded insurance against their existing book and think it’s small. But they should measure it against the market they’re not currently reaching. That’s where the real opportunity is.
What platforms actually want from insurance partners
Most traditional insurers approach platforms transactionally. “We have products. You have customers. Let’s do a deal.”
Platforms want partners who’ll co-create products based on their customer data. Who can iterate quickly when something isn’t working. Who have technology that actually integrates seamlessly. Who understand that the insurance experience is part of the platform’s overall user experience.
A platform launching embedded insurance will evaluate partners on:
Speed of integration (weeks, not months)
Product customization capability (can you design for our specific users?)
Technical reliability (APIs that don’t break)
Claims experience (will this create customer service problems for us?)
Commercial reasonableness (are margins split fairly?)
Traditional insurers often fail on speed and customisation. Their product development cycles are too slow. Their technology can’t handle the integration requirements. Their compliance processes add friction platforms won’t accept.
The insurers’ winning platform partnerships have rebuilt their operating models for speed and flexibility. Separate business units, different approval processes, and product teams that can launch in 6-8 weeks instead of 6-8 months.
The strategic choice traditional insurers face
India’s digital economy is growing at 15-20% annually. UPI transactions crossed 12 billion per month in 2024. E-commerce, digital lending, and gig economy platforms are all expanding rapidly. Insurance will be embedded in all of it.
The question isn’t whether embedded insurance will grow. It will. The question is which insurers will capture that growth.
Right now, there’s a land grab happening. Major platforms are choosing insurance partners. Once a platform integrates with one insurer, builds workflows, and starts seeing results, switching is hard. First-mover advantage matters.
Traditional insurers who dismiss embedded insurance because their initial experiments failed are missing what’s happening. The insurers who figured out the product design, economics, and technology are now signing multi-year partnerships with major platforms. Those partnerships will compound over time.
The window to be a preferred partner rather than a backup option is narrowing. Not because embedded insurance is some urgent trend, but because the platforms driving India’s digital economy are making partnership decisions right now.
What actually needs to happen
For traditional insurers serious about embedded insurance, half measures don’t work. Small pilots with leftover budgets and no organisational commitment just confirm biases that “it doesn’t work.”
What does work:
Dedicated teams with digital product expertise, not traditional insurance people doing this part-time
Real technology investment in modern infrastructure, not APIs wrapped around legacy systems
Products rebuilt for embedded contexts, not existing products slightly modified
Partnership approach that accepts platform economics and requirements
This requires organisational commitment. Budget, senior leadership support, willingness to operate differently than traditional distribution.
Insurers not willing to make that commitment should be honest about it. Embedded insurance done poorly is worse than not doing it at all. But insurers who are willing to do it properly have a genuine opportunity to access growth that traditional distribution can’t capture.
The insurers making serious moves in embedded insurance today are positioning themselves for the next decade of distribution in India. The ones waiting are hoping traditional channels remain viable long enough that it doesn’t matter.
One of those bets will be right.
At Assurekit, we work with insurers to build embedded protection programmes that actually work. We provide the technology infrastructure, product design, and platform integrations that turn embedded insurance from an expensive experiment to a meaningful premium contributor. If you’re evaluating what it takes to succeed in embedded insurance, not just participate, we should talk.

Written by